Skip to content
You can now search across every topic, entity and event.What's new
Iran Conflict 2026
21JUN

Three P&I clubs pull Gulf war risk cover

4 min read
17:51UTC

Three major P&I clubs cancelled war risk coverage for the Persian Gulf. Even if the fighting stops tomorrow, commercial ships cannot legally transit.

ConflictDeveloping
Key takeaway

The insurance withdrawal creates an autonomous financial blockade that operates on its own institutional timeline and will outlast any ceasefire by weeks, accumulating economic damage past the political end-point of the conflict.

American Steamship Owners Mutual P&I, London P&I Club, and Skuld (Assuranceforeningen) — three of the world's major Protection & Indemnity clubs — issued cancellation notices for War risk coverage across The Persian Gulf and Gulf of Oman, effective approximately 72 hours from 2 March.

P&I insurance underwrites third-party liability for commercial shipping: crew injury, pollution, cargo damage. Without active P&I coverage, a vessel cannot be financed by any major maritime bank or commercially operated by any major shipping line. When CMA CGM, Maersk, Nippon Yusen, Mitsui, and Kawasaki Kisen halted Hormuz transits on 1 March , those were operational decisions — reversible within hours if conditions changed. The P&I cancellations are structural. Reinstatement requires a full syndicated risk reassessment across multiple underwriting syndicates. Each club must individually evaluate the residual threat environment, consult reinsurers, and recalculate exposure.

The last comparable insurance withdrawal from The Persian Gulf occurred during the Iran-Iraq Tanker War of 1984–1988, when Iraqi and Iranian forces attacked more than 400 commercial vessels. The collapse of War risk coverage drove the US Navy's Operation Earnest Will in 1987 — Kuwait re-flagged eleven tankers under the American flag because they could no longer obtain commercial insurance at any price. Coverage was not fully restored until months after the August 1988 ceasefire. The current conflict has produced more severe disruption in four days than the Tanker War generated across four years, because the Tanker War left the strait itself passable; this one has not.

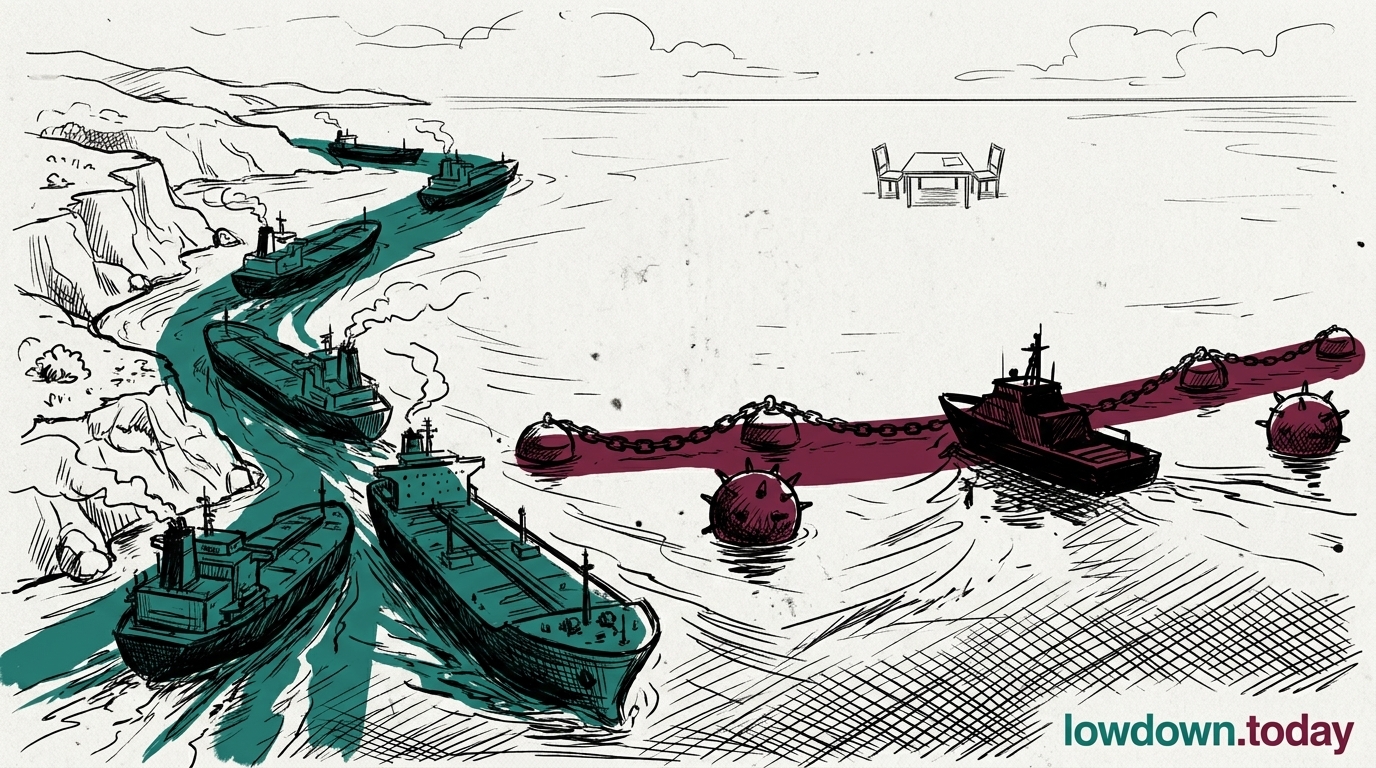
The cancellation creates a second closure of the strait of Hormuz — financial rather than military — that diplomats cannot negotiate away. Iran's Expediency Council secretary Mohsen Rezai declared the strait 'officially open' on 28 February while simultaneously designating US warships as 'legitimate targets.' The declaration satisfied no insurer and no shipowner. A ceasefire, when it comes, stops the fighting. It does not reinstate P&I coverage. The economic damage to global energy supply chains will persist on the insurance market's timeline, not the battlefield's.

Deep Analysis

In plain English

Ships need insurance to dock at ports, secure bank financing for their voyages, and get cargo owners to load their goods. Without it, the entire commercial shipping system seizes up legally and financially. Three of the world's biggest ship insurance clubs have pulled coverage from the Persian Gulf. Even if a peace deal were signed today, ships could not simply sail back through the Strait of Hormuz — each club would have to conduct a full risk review and vote to reinstate, a process that takes weeks. The military blockade and the financial blockade are running on different clocks, and the financial one cannot be ended by a ceasefire.

Deep Analysis
Synthesis

The insurance withdrawal creates a structural asymmetry in conflict resolution: hostilities can end by political decision at any moment, but the economic blockade runs on institutional infrastructure — JWC area listings, syndicate risk committees, International Group of P&I Clubs consensus processes — that does not respond to government timelines. The longer the JWC listing persists, the more shipping companies will re-route infrastructure: new port contracts, alternative supply relationships, long-term logistics arrangements. Some of this reorientation will not revert when coverage resumes, meaning the conflict imposes persistent structural changes on global shipping patterns beyond its military duration.

Root Causes

P&I clubs operate on annual policy years with war risk exclusions triggered by Joint War Committee Listed Areas designations. The Persian Gulf was likely already on the JWC Listed Areas following prior tensions; the formal cancellation notices represent clubs activating pre-existing contractual rights rather than making a novel underwriting judgement. Reinstatement requires JWC delisting, which requires consensus across Lloyd's market underwriters — a body that has historically lagged military developments by two to eight weeks. This structural lag is not a market failure; it is a designed feature of prudential risk management.

What could happen next?
2 consequence2 risk1 meaning
  • Consequence

    Alternative Cape of Good Hope routing adds 10–14 days voyage time and approximately $1–1.5 million additional bunker cost per VLCC round trip, reducing effective global tanker capacity regardless of Hormuz traffic levels.

    Immediate · Assessed
  • Risk

    The weeks-long insurance reinstatement lag means economic disruption accumulates past any ceasefire date, creating a political economy of continued pain that may not align with military or diplomatic objectives.

    Short term · Assessed
  • Meaning

    The withdrawal demonstrates that financial market infrastructure — not only military action — can function as a blockade mechanism, establishing a precedent with implications for how future conflicts in strategically critical waterways are prosecuted.

    Long term · Suggested
  • Risk

    Shipping companies re-routing through alternative corridors are establishing new port contracts and logistics chains; a portion of this infrastructure reorientation will persist after Hormuz reopens, permanently altering Gulf export dependency.

    Medium term · Suggested
  • Consequence

    LNG and crude oil importers in South Korea, Japan, and India — the primary Hormuz-dependent economies — face acute near-term supply disruption irrespective of military outcome or ceasefire timing.

    Immediate · Assessed
First Reported In

Update #14 · Natanz unverified; Hormuz sealed

Insurance Business· 3 Mar 2026
Read original
Different Perspectives
Shipping and insurance industry
UKMTO counted about 20 US-facilitated Hormuz transits a day to 11 September against only 6 visible on AIS, with traffic still around 90% below the 138-a-day pre-war baseline. War-risk underwriters cannot price hulls they cannot see, or resolve whether the tanker El Gaia hit a mine, as Iran claims, or a missile and drone, as CENTCOM says.
European refiners
European refiners
European refiners, including Poland's Orlen, absorbed a roughly $26 gap between Dated Brent at $130.80 on 15 September and ICE Brent futures settling at $103.87 on 18 September, a spread that widened from $13.45 on 9 September rather than newly opening. Their futures hedges no longer cover what they now pay for physical barrels.
Saudi Arabia
Saudi Arabia
Saudi Aramco zeroed European term customers' October allocations and rerouted roughly 60 million barrels to Asia through Ras Tanura and Sohar, using Red Sea and Gulf terminal capacity built years ago to cut Hormuz exposure. Riyadh reallocated existing supply rather than negotiating a shortfall with Europe.
Qatar
Qatar
Qatar's energy minister Saad al-Kaabi told Bloomberg at the Qatar Economic Forum on 20 September that Bessent's two-year Hormuz-obsolescence forecast is wrong, and that Doha has deliberately built no bypass pipeline. Qatar's gas exports run through one waterway by choice, not oversight.
Iran (foreign ministry and Majlis)
Iran's foreign ministry and 130 Majlis deputies moved toward NPT withdrawal this week, with lawmaker Hossein-Ali Haji Deligani filing a triple-urgency bill on 20 September that Speaker Qalibaf has not yet scheduled. Tehran treats treaty membership as leverage still on the table, not yet spent.
Russia and China
Russia and China
Moscow and Beijing vetoed the Panel of Experts' renewal, maintaining Resolution 2231 lapsed in October 2025 and the 2025 snapback was never validly triggered, so the sanctions architecture the Panel enforces has no current legal standing. Both governments frame the veto as upholding law, not shielding Tehran.